The Sapphire Reserve is a premium travel card with a premium price: 795 dollars a year. Chase's argument is that the points, lounges and credits add up to more than the fee. That can be true, but only if you spend on the right things and use the credits. This guide goes through what Chase lists in October 2026, a worked comparison against the 95-dollar Preferred, and the cases where you should keep the cheaper card.
The card at a glance
- 795 dollars
- Annual fee
- 8x
- Chase Travel
- 4x
- Booked direct
- 0
- Foreign transaction fees
Charged yearly
Flights, hotels, rental cars, cruises, activities and tours
Flights with an airline and hotels with the hotel
Per Chase's page
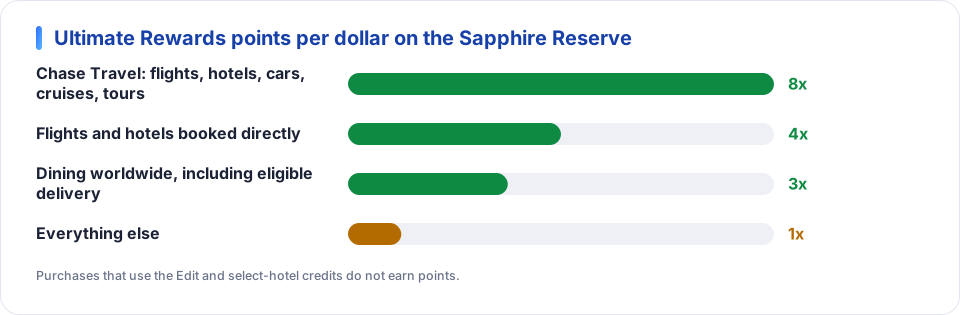
Chase also says the points are worth up to 2 cents each on top-booked hotels and on premium cabin tickets with selected airlines through Chase Travel. It marks these as Points Boost offers, which appear in search results for some bookings only. Elsewhere the default value is lower, so treat 2 cents as a ceiling, not an average.
The credits and perks
| Perk | Value | The catch |
|---|---|---|
| Travel credit | Up to 300 dollars a year | Chase's benefit terms define which purchases count. |
| The Edit | Up to 500 dollars a year | Maximum 250 per transaction, two-night minimum, selected hotels only. |
| Selected Chase Travel hotels | Up to 250 dollars | Prepaid stays with IHG, Montage, Pendry, Omni and other listed brands, to 31 December 2026. |
| Dining | Up to 300 dollars a year | 150 from January to June and 150 from July to December, at Sapphire Reserve Exclusive Tables restaurants. |
| StubHub and viagogo | Up to 300 dollars a year | 150 per half-year, activation required. |
| Apple TV and Apple Music | A 324-dollar yearly value | The offer runs to 22 June 2027. |
| DoorDash | Up to 420 dollars a year in promos, plus DashPass | Monthly promos, so unused months are lost. |
| Lyft | Up to 120 dollars a year | Monthly in-app credits, plus 5x total points, to 30 September 2027. |
| Peloton | Up to 120 dollars a year | Plus 10x on eligible hardware, up to 50,000 points. Activation required. |
| Trusted traveller | Up to 120 dollars every four years | TSA PreCheck, Global Entry or NEXUS fee. |
| IHG One Rewards | Platinum Elite status | Until 31 December 2027, after you link your IHG account. |
Chase also lists a Reserve Travel Designer service, valued at up to 300 dollars a trip, and credits that unlock after 75,000 dollars of spending in a calendar year, including Southwest Airlines statement credits through Chase Travel. For lounges, Chase lists Chase Sapphire Lounges by The Club with up to two guests, selected Air Canada lounges and more than 1,300 Priority Pass lounges. See airport lounge access in 2026 for how access rules differ between programmes.
Does the 795-dollar fee pay for itself?
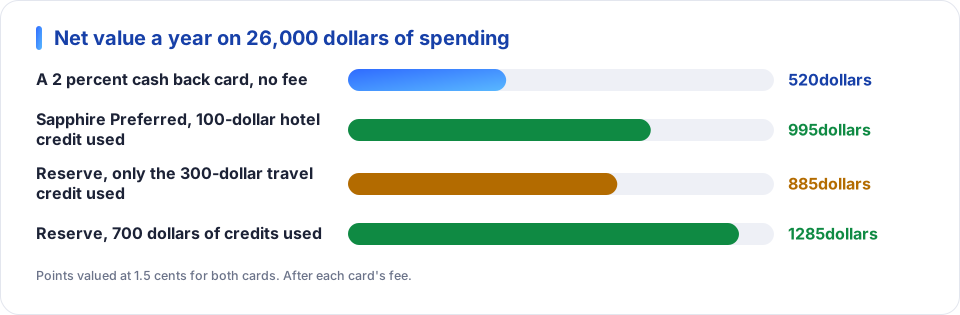
The sums above value points at 1.5 cents for both cards. The Reserve's higher ceiling, up to 2 cents, would add another 460 dollars on the same points, but only on bookings where a boost appears. Transfers to airline and hotel partners can be worth more than either figure, and they are available on both cards. See what points are worth.
Protections
Chase lists trip cancellation and interruption cover of up to 10,000 dollars per traveller and 20,000 per trip, emergency evacuation and transportation up to 100,000 dollars, and primary rental car cover up to 75,000 dollars. Travel delay cover pays up to 500 dollars per traveller after six hours or an overnight stay. Baggage delay pays up to 100 dollars a day for five days. Roadside help is covered up to 50 dollars per incident, four times a year. For purchases, return protection covers up to 500 dollars per item and 1,000 a year within 90 days, purchase protection covers 120 days up to 10,000 per item, and warranties of three years or less get an extra year. How these covers fit together is in card travel protections and insurance.
Eligibility and the application
Chase shows your own new-cardmember offer, and the amount changes, so this guide does not quote one. A Sapphire bonus can depend on the other Sapphire cards you hold or have held, and on how many cards you have opened recently.
Is it right for you?
Fits you
- You book several trips a year through Chase Travel, or you already spend on dining.
- You will use the 300-dollar travel credit and at least two or three of the other credits for things you buy anyway.
- You fly often enough that lounge access changes your trips.
Think twice
- You rarely travel, or you book airlines and hotels directly for status.
- You would be paying for credits you have to chase each month.
- A no-fee card with a flat return would earn nearly as much on your spending.
See also which US cards are worth getting by spending style.
Questions people ask
What does the 300-dollar travel credit cover?
Chase's page describes up to 300 dollars a year toward travel purchases and calls it the most flexible travel credit available. Chase's benefit terms define which purchases count, so read them before you rely on a specific airline or hotel charge.
How do The Edit and the select-hotel credits work?
The Edit credit is up to 500 dollars a year, with a maximum of 250 per transaction, for prepaid bookings of at least two nights. A separate 250-dollar credit on selected Chase Travel hotels runs to 31 December 2026. Qualifying purchases do not earn points.
Which lounges can I use?
Chase lists Chase Sapphire Lounges by The Club with up to two guests and more than 1,300 Priority Pass lounges worldwide. It also lists selected Air Canada Maple Leaf Lounges and Cafés with an eligible boarding pass, and says new lounges are coming in 2026.
Does the Reserve charge foreign transaction fees?
No. Chase's page says you can spend anywhere in the world with no foreign transaction fees.
Should I get the Preferred or the Reserve?
The Preferred suits people who want points at a low fee. The Reserve suits people who will use the credits and lounges. The comparison guide sets the two side by side.
Sources
Written from these pages and checked against them on October 9, 2026. Programs and rules change, so check the provider’s current terms before you decide.
Cards in this guide
General information, not financial, legal or travel advice. Your own card terms and the provider’s current rules always come first.