Most no-fee cash back cards pay a flat 2% or less. This one pays 3% where you choose, 2% on groceries and warehouse clubs, and pays more if you keep money with the same bank. It also lets some newcomers with no SSN start a credit history. That makes it unusual, and the numbers worth working out.
The earning structure
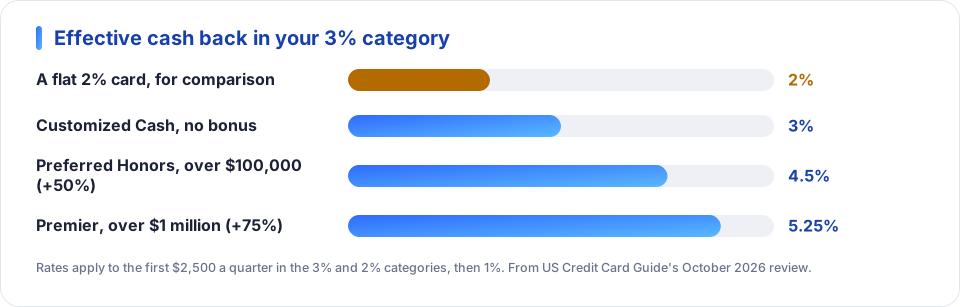
You choose your 3% category from six: online shopping together with cable, streaming, internet and phone plans, dining, travel, gas and EV charging, drug stores, and home improvement and furnishings. Online shopping is the broad choice. Grocery stores and wholesale clubs pay 2%, and everything else pays 1%. The 3% and 2% apply only to the first $2,500 a quarter combined. After that, the rate is 1%.
What the bonus is worth
- $75
- The 3% rate on the full $2,500 cap
- $131
- The same cap at 5.25% with the 75% bonus
- $325
- The extra a year over a flat 2% card at the cap
2,500 x 3% a quarter
2,500 x 5.25% a quarter
10,000 x (5.25% - 2%)
So the top tier adds about $56 a quarter over the unboosted card, and about $325 a year over a flat 2% card, assuming you spend the cap in a single category. To qualify you need over $1 million at Bank of America or Merrill Edge. At that size, the interest or return on those assets dwarfs the card bonus. The tiers are a perk for people who already bank there, not a reason to move money.
Application rules
Mind the 2/3/4 rule
The reported limit is two cards in two months, three in twelve and four in twenty-four. Applications that break it may be approved and then closed as approved in error.
Check the 24-month rule
You cannot get the card if you hold it or held it in the past 24 months. Co-branded versions are separate products.
Choose online or branch
The $200 sign-up bonus after $1,000 in spend within three months is only for online applications.
Be aware of the foreign fee
The card charges a foreign transaction fee, so keep it for US spending. See cards with no foreign transaction fee.
If you have no SSN or credit history
The 2026 review says the card can be approved with no SSN and with no credit history if you apply in person at a branch. That route does not earn the online sign-up bonus, which for a first card is usually a small loss. Bring the identity documents the bank asks for. Never use a made-up or borrowed number: an application with false identity details is a serious problem, not a shortcut. For other first-card routes, see building credit as a newcomer and secured credit cards.
When you are ready for more rewards, see the best cards by spending style.
Questions people ask
Do I have to bank with Bank of America to get the card?
No. The 3% category, 2% groceries and 1% base apply to everyone. The 50% and 75% bonuses require qualifying balances at Bank of America or Merrill Edge.
What is the 2/3/4 rule?
Bank of America reportedly approves at most two cards in two months, three in twelve and four in twenty-four. An application that breaks it can be approved and then closed as 'approved in error'.
Can I get this card again?
Not if you hold it or held it in the past 24 months. There are several co-branded versions that count as separate products.
Sources
Written from these pages and checked against them on October 6, 2026. Programs and rules change, so check the provider’s current terms before you decide.
General information, not financial, legal or travel advice. Your own card terms and the provider’s current rules always come first.