Digital banks are fast, but many visitors still want a traditional account with a debit card, a branch to visit and a bigger product list. Two names dominate: Bank of China (Hong Kong), or BOCHK, and HSBC. This guide sets out what each reportedly asks for, so you can decide whether to apply and what to prepare.
Side by side
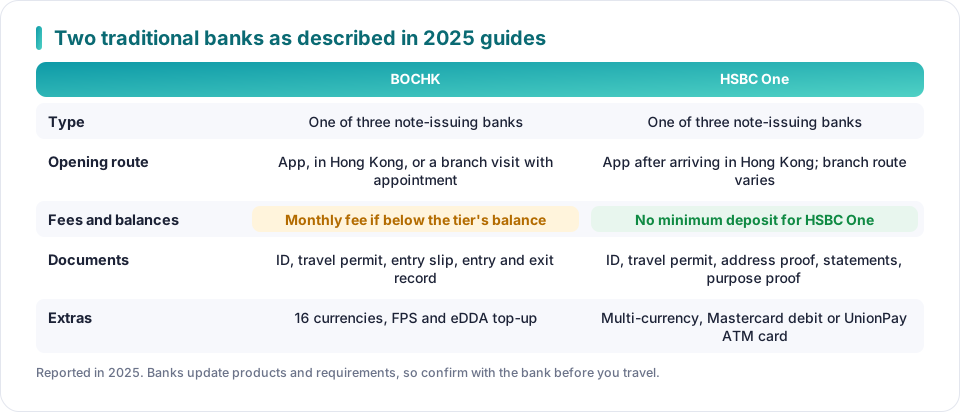
BOCHK: tiers, limits and the first week
BOCHK reportedly offers three personal tiers. The monthly fee applies only if your daily balance falls below the tier's requirement.
| Tier | Daily balance asked | Monthly fee if below |
|---|---|---|
| Entry | HK$10,000 | HK$60 |
| Middle | HK$200,000 | HK$120 |
| Top | HK$1,000,000 | HK$300 |
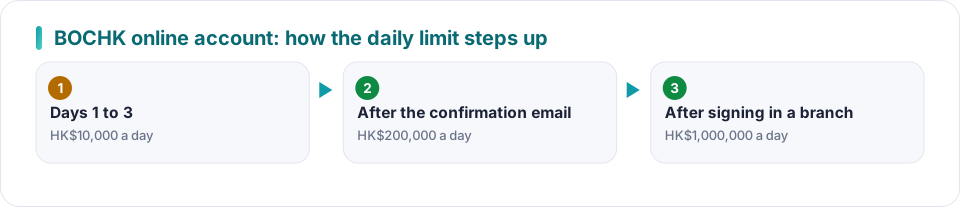
An account opened online gets a lower limit at first.
HSBC: documents and purpose
For HSBC One, the 2025 guide lists these documents, with identity documents valid for at least six more months:
Identity
A valid ID card, a travel permit or passport, and the slip printed at the border gate.
Address proof
A document from the past three months, sent directly to you by a utility, bank or phone company. Tax-stamped rental contracts also count.
Statements
Three to six months of bank statements showing income and balance.
Purpose proof
If you say you invest, bring evidence of that experience such as recent fund or brokerage statements.
The guide's own summary is worth repeating: the bank wants to see a normal customer who will keep money or transact with it, and who has a basic financial footing.
Truth beats clever
Prepare a real reason
Study, work, family, regular travel or documented investing are all legitimate. Do not invent one.
Match your story across documents
Job, address and income must agree between your forms, statements and what you say to the staff.
Keep roaming on
Both banks send verification codes by text. Turn on roaming or buy a local SIM. See Hong Kong trip kit.
Read the terms before you apply
Fees, limits and product features change often.
After the account opens
A traditional account is most useful when it is connected to the places you spend. Once it is live, the sensible order is to switch on the Faster Payment System so you can receive and send transfers by phone number, set a transfer limit that matches your trip, and then link the card to a wallet. For the wallet step, see linking a Hong Kong bank card to AlipayHK. If you will hold several currencies, compare the bank's rates with a multi-currency account before you move large sums.
Tell your tax office
Opening an account abroad does not make it invisible. Many countries exchange account information under the OECD's Common Reporting Standard, and some require residents to report foreign accounts or the interest they earn. Check the rules of the country where you are tax resident before you open the account, and keep your statements.
Compare with Hong Kong and Macao digital banks and read deposit insurance explained.
Questions people ask
Do I need a Hong Kong address to open an account?
HSBC lists a recent address proof as required, and says acceptable proof is a document sent directly to you by a utility, bank or government body. A visitor's home address abroad may qualify if it is on those documents. Always check the bank's current list.
Can I walk into a branch without an appointment?
It depends on the bank and the branch. Guides report that appointments improve success and that busy central branches have long queues and stricter reviews. Check the bank's own booking page.
What counts as a good reason for opening an account?
A true one: study, work, family, regular travel or investing you can demonstrate. Vague answers or purposes you cannot support often lead to refusal or later questions.
Sources
Written from these pages and checked against them on October 6, 2026. Programs and rules change, so check the provider’s current terms before you decide.
General information, not financial, legal or travel advice. Your own card terms and the provider’s current rules always come first.