When people say "check your credit", they mean three companies. But the Consumer Financial Protection Bureau keeps a list of dozens of other consumer reporting companies, grouped by the industries they serve. If you are declined for a bank account, a lease, a job, a phone plan or an insurance quote, the file behind the decision may not be the one you have been checking.
Which file sits behind which decision
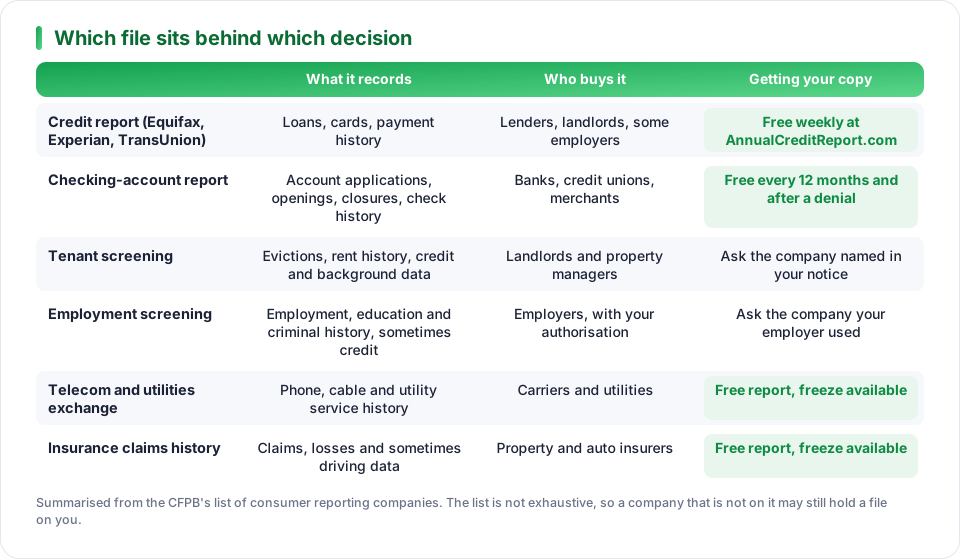
The ones most people meet first
Checking-account reports
When you apply for a checking or savings account, the bank often asks a checking-account reporting company about you. The CFPB names Certegy Payment Solutions, TeleCheck Services, CrossCheck, ChexSystems, Early Warning Services and Global Payment Check Services. ChexSystems says its clients report closed accounts, forcibly closed accounts and related history, and that it keeps reported information for five years. A good credit score does not cancel a poor checking-account report, so check it before you open accounts, especially if you are chasing several bank sign-up bonuses.
Tenant and employment screening
Tenant screening companies compile evictions, rent payment history and credit data for landlords. If you are rejected, or accepted with harsher terms such as a bigger deposit or a co-signer, the landlord must give you an adverse action notice that names the screening company. Employment screening companies hold what an employer asked for with your authorisation. Ask for the company's name when you sign, and know that employers must follow certain steps before turning you down because of a background report.
Telecom, utilities and insurance
Phone, cable and utility providers share service history through an exchange, and insurers buy claims and loss history. The CFPB's list marks the National Consumer Telecom and Utilities Exchange and LexisNexis C.L.U.E. as companies that offer a free report and a freeze, which is worth knowing before a move abroad or a new contract.
How to see and fix your own files
Find the company
Use the CFPB list, filter by market area, and note the names that fit your situation. The adverse action notice also names the company.
Ask for your free copy
For the companies that provide one, the CFPB says to expect a free report every 12 months, another after an adverse action notice and delivery within 15 days.
Read it line by line
Look for accounts that are not yours, closed accounts that were paid, and mixed-up names or addresses. See reading your credit report.
Dispute what is wrong
Write to the company and the source, keep proof and note the dates. See your rights under the FCRA.
Consider a freeze
Some specialty companies let you freeze the file. Pair that with the credit freezes and fraud alerts you may already use.
Questions people ask
Is a ChexSystems report the same as a credit report?
No. It covers checking and savings account applications, openings and closures and check-writing history, not your loans and cards. It is possible to have a great credit score and a poor checking-account report.
How do I find out which company a lender or landlord used?
After a decline, the bank or landlord must send an adverse action notice that names the reporting company. Before a job check, ask which screening company will be used when you give your authorisation.
Do these checks lower my credit score?
Per the CFPB, employment screening and telecom or utility checks do not affect your credit scores. A landlord who pulls your credit report may do so as a hard inquiry, which can lower your scores slightly.
Sources
Written from these pages and checked against them on October 6, 2026. Programs and rules change, so check the provider’s current terms before you decide.
General information, not financial, legal or travel advice. Your own card terms and the provider’s current rules always come first.